14 Nov , 2026 By : Shambhavi Mishra
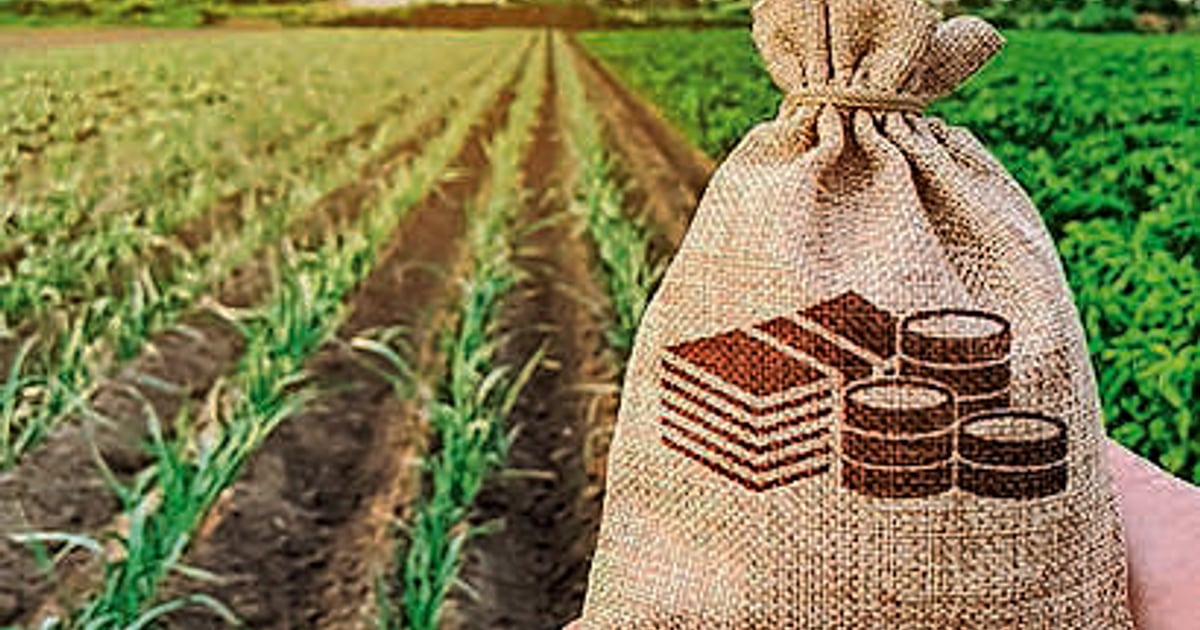
? Quick Take: Agricultural non-performing assets have spiked to 5.1 percent, vastly outpacing corporate and retail risk pools. For bank investors, this underlying rural stress warrants a closer look at credit books before the next earnings cycle.
While corporate balance sheets have largely cleaned up their acts over recent years, a quieter storm is brewing on the rural front. Agricultural lending has suddenly emerged as the single biggest asset-quality headache for Indian lenders. Gross bad loans in farm credit portfolios now sit at an uncomfortable 5.1 percent. That metric towers over industry and service sector NPAs, which are currently tamed at a modest 1.5 percent.
Erratic weather patterns and uneven monsoon distribution have taken a heavy toll on crop yields across key agrarian belts. When harvests fail or fall short, farm incomes take an immediate hit, directly compromising servicing capabilities for crop loans and Kisan Credit Card accounts.
Several commercial lenders have reported rising slippages in their agricultural books over recent quarters. Even though systemic agricultural bad loans have technically trended lower compared to the 2020-21 peaks, the sudden velocity of fresh stress has forced credit risk teams back onto high alert.
For years, analysts worried about large corporate defaults dragging down public sector banks. Today, the script has flipped completely. Corporate India has deleveraged, leaving bad-loan ratios for industrial and service portfolios remarkably low.
Agriculture, by contrast, operates at the mercy of elements far beyond a banker's control. A single deficient monsoon season ripples straight through rural consumption demand and translates into sticky bad debts on institutional balance sheets.
Source Attribution: Originally reported by et-banking-finance (https://economictimes.indiatimes.com/industry/banking/finance/banking/agricultural-loans-pose-major-asset-quality-risk-for-indian-banks-with-5-1-npa-ratio-in-q2-2026/articleshow/135667964.cms).
Disclaimer: The financial, market, and corporate developments published above are reported for informational and educational purposes only. GrowMudra does not provide investment advice or stock recommendations. Readers are strongly advised to consult a SEBI-registered financial advisor before making investment decisions.
0 Comment