18 Nov , 2026 By : Shambhavi Mishra
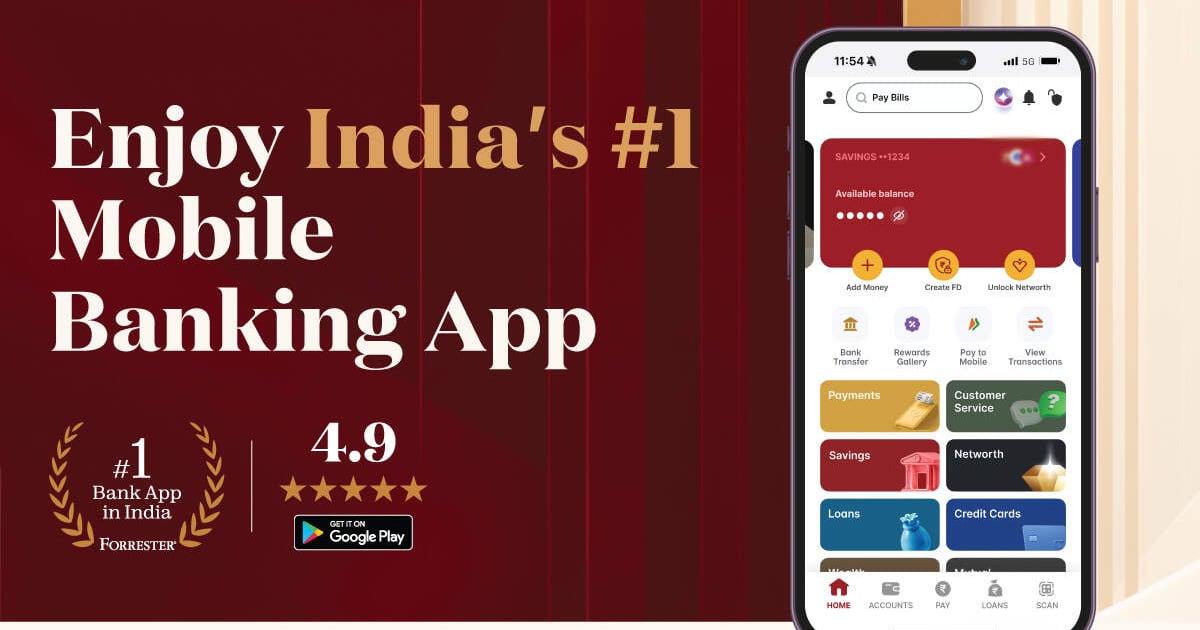
? Quick Take: Having a banking app is now a baseline requirement, not a competitive advantage. The real differentiator is the seamless integration of payments, savings, and investments into a single, frictionless ecosystem.
For years, banks raced to launch flashy mobile applications, treating them as digital storefronts. That era is over. UPI has fundamentally reset customer expectations, making simple transactions a commodity. Today, the question isn’t whether a bank has an app, but how effectively that app serves as a unified financial hub. If your banking app still feels like a siloed utility rather than an integrated ecosystem, you are watching the future of retail banking slip away.
The shift is driven by user behavior. Indian consumers no longer want to juggle separate interfaces for paying bills, managing savings, and investing in mutual funds. They expect a single point of entry. Banks that fail to bridge these gaps are losing relevance. The technology exists; the challenge is architectural. It requires breaking down internal silos to allow data and services to flow freely between payment, credit, and investment modules. This is where legacy systems often stumble, while agile digital-native players gain ground.
Consider the customer journey. A user receives a salary credit, pays rent via UPI, and then invests the surplus. If these three actions require logging out, navigating different menus, or even switching apps, the experience is broken. Seamless integration means the bank anticipates the next step in the financial lifecycle. It turns a transactional interaction into a relational one. This stickiness is what drives long-term customer value and reduces churn in a highly competitive market.
Source Attribution: Originally reported by et-banking-finance (https://economictimes.indiatimes.com/industry/banking/finance/banking/when-every-bank-has-an-app-what-actually-makes-digital-banking-different/articleshow/135709949.cms).
Disclaimer: The financial, market, and corporate developments published above are reported for informational and educational purposes only. GrowMudra does not provide investment advice or stock recommendations. Readers are strongly advised to consult a SEBI-registered financial advisor before making investment decisions.
0 Comment