26 Jul , 2022 By : Monika Singh
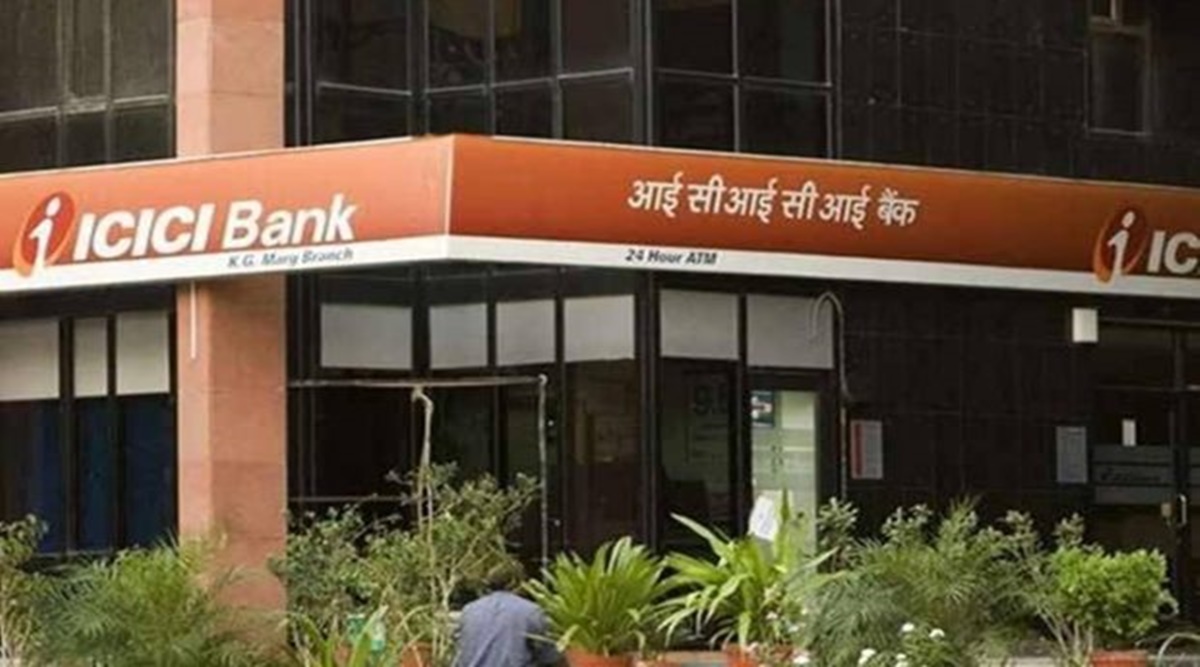
ICICI Bank (ICICI) delivered a solid quarter, the seventh in a row, outperforming consensus PAT by 17% and beating peers HDFC Bank and Kotak on loan growth, NII growth, treasury and GNPLs. Opex exceeded expectations due to employee pay-outs and branch additions. The bank posted a trading gain of Rs 360 mn versus a loss by peers. While GNPLs declined q-o-q, ICICI continued to fortify its balance sheet by making higher prudential provisions of 47bp of loans.
All in all, we are increasing the target multiple to 3x (from 2.5x) Sep-23E and TP to Rs 1,020 (from Rs 950) backed by ICICI’s consistent delivery. ICICI has reported nearly flawless core earnings for the last few quarters, outclassing its peers; reiterate it as ‘Buy’ and top pick.
Strong loan and NII growth, no treasury loss and higher opex: Loans grew 21% y-o-y/4% q-o-q. Retail loans grew 4% q-o-q/22% y-o-y, rural remained flat q-o-q, but grew 8% y-o-y, domestic corporate grew 3% q-o-q/14% y-o-y, international grew 11% q-o-q/14% y-o-y while SME slid 3% q-o-q. Within retail, housing grew 4% q-o-q, credit cards grew 12% q-o-q and personal loans grew 9% q-o-q. The mix of unsecured loans at 10.7% is higher q-o-q (10.2%), but lower than HDFC Bank’s 16%.
NIM is stable at 4.01%. NII grew 5% q-o-q/21% y-o-y, higher than HDFC Bank’s/Kotak’s 3%/4% q-o-q. Core non-interest income stood flat q-o-q (up 25% y-o-y). The bank reported a trading gain of Rs 360 mn amid trading losses by other banks, though it is lower than Rs 0.93 bn q-o-q. Employee expenses ex ESOP cost rose 15% q-o-q due to branch additions (120) and pay-outs. Other opex grew 2% q-o-q while total opex rose 7% q-o-q. Core PPOP grew 1% q-o-q/19% y-o-y. Specific credit cost remained low at 4bp versus 2bp q-o-q while ICICI made prudential provisions of 47bp vs. 48bp q-o-q.
Gross slippages rose sharply q-o-q; net slippages remain negative: While gross slippages rose to 2.8% (2.4% ex-agri) from 2% q-o-q, recoveries were also stronger, leading to a decline of 2% q-o-q in GNPL. Total stressed loans declined to 5.2% from 5.8% q-o-q with GNPL ratio of 3.4% and standard stress of 1.7%. PCR on total stress now stands at a high 78% versus 71% q-o-q—among the highest in the sector.
Outlook and valuation – TP of Rs 1,020; maintain top pick status: We reiterate ICICI as our top pick driven by its consistent and best-in-class earnings delivery, high capitalisation, strong liability franchise and efficient treasury. Our target multiple for ICICI is now on a par with HDFC Bank. We expect RoE of 16% for FY24E for ICICI, higher than the merged RoE of 14% for HDFC Bank.
0 Comment